Credit Note: What It Is, When to Issue One & Examples
Quick answer: A credit note, also called a credit memo, records a reduction to an invoice you have already issued. It can correct an overcharge, recognise a return, or document an agreed discount. A credit note changes the amount billed; a refund moves money back to the customer. They are related, but not interchangeable.
You invoice a client for $1,000. They pay $600. Then you agree to remove a $200 charge because part of the work was cancelled. Do they still owe $400, do you owe them $200, or should you replace the invoice?
The answer is simpler than it first looks: issue a $200 credit note, allocate it to the original invoice, and the remaining amount due is $200. No refund is needed in this example. Getting this distinction right keeps both businesses' records aligned and stops reminders chasing money that is no longer owed.
This guide covers credit note meaning, credit notes versus refunds, worked examples, a copyable document layout, bookkeeping, and tax considerations. All businesses, names, references, and amounts in the examples are fictional. Tax examples are illustrative, not advice for a particular transaction.
What Is a Credit Note?
A credit note is a document issued by a seller to reduce all or part of a previously invoiced amount. It identifies the invoice being adjusted, explains the reason, and shows the value credited. The original invoice and the credit note together explain the corrected transaction.
Suppose a supplier invoices ten items but delivers only eight. Rather than quietly changing the customer's copy after sending it, the supplier can issue a credit note for the two undelivered items. The customer then has evidence for the lower amount payable.
Credit memo is another common name, especially in US accounting software. The label matters less than what the document does and whether it satisfies the rules that apply to your business. Some systems also offer invoice revision or voiding workflows; those are not automatically equivalent to issuing a credit note.
For the underlying payment request, read how to create an invoice. This article focuses on adjustments after invoicing, rather than invoice creation or resolving a disagreement.
For a shorter definition, see our credit memo glossary entry.
Credit Note vs Refund vs Invoice: The Differences
| Item | What it records | Does money move? | Example |
|---|---|---|---|
| Invoice | A charge for goods or services | Not by issuing it alone | Bill a client $1,000 |
| Credit note | A reduction to an invoiced charge | Not by issuing it alone | Reduce that charge by $200 |
| Refund | A payment back to the customer | Yes | Return $200 already collected |
| Receipt | Confirmation of a payment | It documents a payment | Confirm receipt of $600 |
| Customer account credit | Value held for later allocation | Not until refunded or otherwise settled | Hold $200 against a future order |
The key question is: are you correcting the price, settling money already collected, or doing both? An unpaid overcharge usually needs an invoice adjustment without a cash refund. A reduction to a fully paid invoice may need both a credit note and a refund, or an agreed credit against a future purchase.
A receipt does not correct the invoice's value. For a fuller comparison of the original documents, see invoice versus receipt. Likewise, issuing a credit note does not prove that a card refund succeeded. Keep the payment confirmation separately.
Stripe's credit-note documentation illustrates this distinction: a credit note can decrease an open invoice's amount due, while credits on paid invoices need an appropriate refund or customer-balance allocation. Those are Stripe Invoicing behaviours, not a promise that every invoicing application works identically.
When Should You Issue a Credit Note?
Typical reasons include an agreed price reduction, goods returned, an overcharge, incomplete delivery, a cancelled service, or a discount agreed after billing. The common thread is that the amount legitimately charged for the transaction has fallen.
- Billing error: you billed twelve hours instead of ten and agree the correction with the customer.
- Returned goods: a customer returns an eligible item and you approve the return.
- Reduced scope: an invoiced project phase is cancelled under your agreement.
- Post-sale discount: you agree a reduction after the original invoice was issued.
- Duplicate charge: the same deliverable was billed twice and you need to remove the extra charge.
Do not issue a credit just because an invoice is late. An outstanding invoice can still be valid and collectible. Reducing it changes what the customer owes; it is not simply a way to tidy an aging report.
Also separate a commercial price reduction from a bad debt. If a customer owes the full amount but cannot pay, the accounting and tax treatment may involve a write-off or bad-debt rules instead. UK VAT guidance explicitly says a valid VAT credit note must not be issued for a bad debt.
If the reduction is not yet agreed, first establish the correct charge and preserve the evidence. Our invoice-dispute guide covers that separate process. Here, the examples assume the parties have already agreed the adjustment.
Three Credit Note Examples: Unpaid, Partly Paid, and Paid
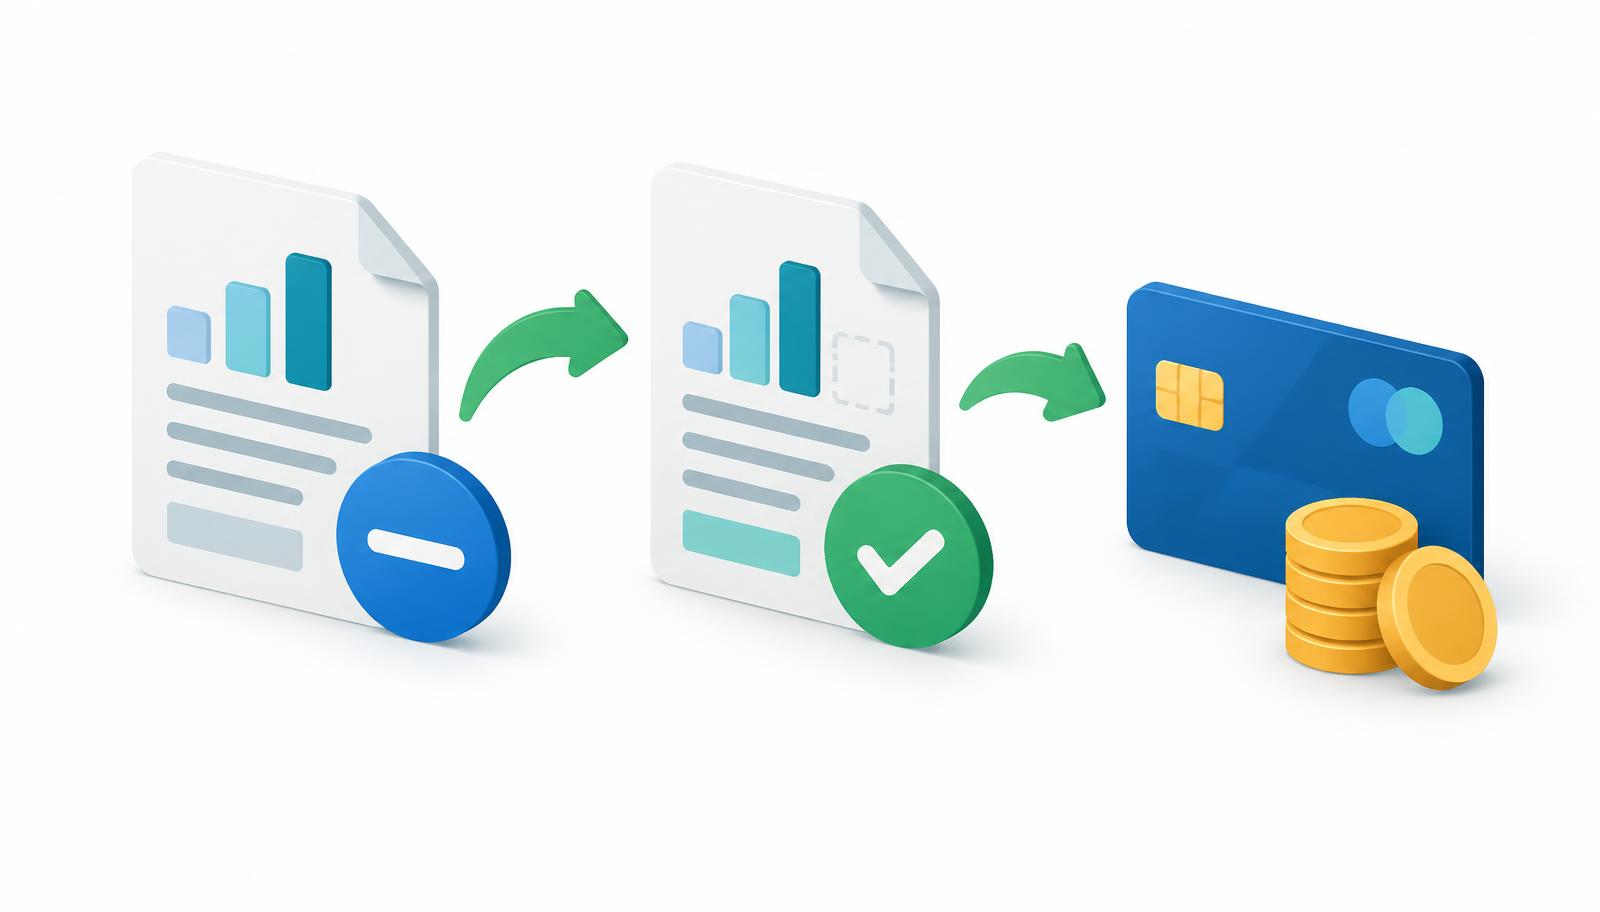
Use the same $1,000 invoice to see how payment status changes the outcome. In these examples there is no tax, no earlier credit, and no processor fee. Each credit is an agreed reduction to the original sale.
Example 1: An unpaid invoice
You billed $1,000, received nothing, and agree a $200 reduction. Issue a $200 credit note and allocate it to the invoice. The revised amount due is $800. No money leaves your bank because the customer has not paid anything.
Send both the credit note and an updated balance statement. Make clear that $800 remains payable, and confirm the relevant payment date. Avoid sending only a document headed “credit,” which a busy accounts-payable team might interpret as money you will return.
Example 2: A partly paid invoice
You billed $1,000, received $600, and agree a $200 reduction. The corrected total charge is $800. Because $600 has already been paid, the customer still owes $200.
Remaining balance = original invoice total − allocated payments − allocated credits. For this example: $1,000 − $600 − $200 = $200. This formula assumes those payments have not been reversed and the credits are actually allocated to this invoice.
A refund would be a separate cash movement. Do not return $200 automatically merely because the credit note is for $200: in this scenario, the customer has paid less than the corrected charge.
Example 3: A fully paid invoice
You billed $1,000, received $1,000, and agree a $200 reduction. The corrected charge is $800, so the customer now has $200 of excess payment to settle.
You can return $200 or, where permitted and agreed, hold it as a customer credit for a future invoice. Document the choice. Do not assume that a future-purchase credit is acceptable when the customer is entitled to a refund.
| Original charge | Payment received | Credit issued | Result |
|---|---|---|---|
| $1,000 | $0 | $200 | Customer owes $800 |
| $1,000 | $600 | $200 | Customer owes $200 |
| $1,000 | $1,000 | $200 | $200 excess payment to refund or hold as agreed credit |
| $1,000 | $600 | $500 | $100 excess payment to settle |
The last row is the useful edge case. Even a partly paid invoice can create a refund obligation if the credit reduces the final charge below the amount already collected: $1,000 − $500 = $500, compared with $600 paid.
What Should a Credit Note Include?
A useful credit note should let someone who was not involved reconstruct the correction. Include the following information, then check any additional tax or local invoicing requirements.
- A clear heading: Credit Note or Credit Memo.
- A unique credit-note reference and issue date.
- Your business details and the customer's correct legal details.
- The original invoice number and, preferably, its date.
- A specific reason for the adjustment.
- Descriptions, quantities, and amounts of the affected items.
- The net reduction, relevant tax breakdown, and total credit.
- The currency, matching the transaction being corrected.
- How the credit will be allocated, refunded, or held.
- The remaining amount payable, where helpful and accurately calculated.
Use identifiable references, such as INV-0042 for the invoice and CN-0018 for its credit note. A separate credit-note series is a practical organisation choice, not a universal rule for every country. Our invoice-numbering guide explains how to keep references traceable.
Do not call every reduction a “refund” in the reason field. “Two undelivered items from invoice INV-0042” explains what changed. “Refund” only describes a possible way to settle it.
A copyable credit-note layout
CREDIT NOTE CN-0018
Issue date: [date]
Seller: [legal business name and address]
Customer: [legal customer name and address]
Original invoice: INV-0042, issued [date]
Reason: Agreed cancellation of one project deliverable
Net amount credited: $200.00
Tax adjustment: $0.00 in this fictional example
Total credit: $200.00 USD
Allocation: Applied to INV-0042
Original invoice total: $1,000.00
Payments already allocated: $600.00
Remaining balance: $200.00
Payment date: [confirmed date]
This is a practical starting layout, not a universally compliant tax template. Add registration numbers, tax rates, original supply details, and other fields required in your jurisdiction. Have your accountant check it before using it for tax adjustments.
How to Issue and Process a Credit Note: Seven Steps
1. Confirm exactly what changed
Record the agreed reduction, the affected items, and whether the amount includes tax. Keep the approval, return confirmation, or contract variation alongside the transaction. This prevents a later disagreement over what the credit covered.
2. Check the original invoice and payments
Confirm the customer, currency, invoice reference, payments received, earlier credits, and any refunds already made. Check the ledger and bank or processor records rather than relying on an email saying “we paid it.”
3. Calculate the adjustment
Credit only the affected amount. If an invoice contains several tax rates, identify which lines changed rather than reducing the invoice using an arbitrary blended rate. Check rounding and whether discounts were already included.
4. Create a traceable document
Use your accounting system's credit-note function where available. Reference the original invoice, explain the correction, and save the document in the customer record. Do not assume a negative line in an ordinary invoice produces the correct tax or ledger treatment.
5. Allocate the credit and choose settlement
Apply it to the intended invoice or record the customer credit as appropriate. If a refund is due, confirm the method and process it separately. Obtain agreement before moving value to a different invoice or future purchase when that choice needs the customer's consent.
6. Send the credit note and clear balance
Tell the customer what changed, how much remains due, or what will be returned. Ask their accounts-payable team to allocate the credit against the same invoice. A correct document sitting in the wrong inbox can still leave both ledgers mismatched.
7. Reconcile and update reminders
Verify that the invoice balance, customer statement, payment record, and tax records agree. Stop reminders for credited amounts. Resume collection only for the legitimate remaining balance, using an appropriate invoice reminder schedule.
Can You Pay That's tools can help with original invoice preparation and follow-up wording, but this guide does not imply a dedicated credit-note or refund workflow is available in the app. Use your accounting system for the adjustment and your payment provider for any refund.
Credit Note Accounting: Seller and Buyer Examples
The document should reach both parties' books. These simplified examples use accrual bookkeeping, exclude tax, and assume the sale and purchase have already been recorded. Your account names and entries may differ, especially for inventory, capital assets, deferred revenue, cash accounting, or previously closed periods.
Seller: reduce the sale and receivable
For a $200 reduction on an unpaid invoice, the seller might debit a sales-returns-and-allowances account by $200 and credit accounts receivable by $200. That lowers the receivable without recording a payment.
| Seller account | Debit | Credit |
|---|---|---|
| Sales returns and allowances | $200 | — |
| Accounts receivable | — | $200 |
For the partly paid $1,000 invoice, the earlier $600 receipt and this $200 credit leave $200 receivable. The credit is not another cash receipt, and it should not inflate the amount shown as collected from the customer.
Buyer: reduce the payable and purchase cost
In a simple expense example, the buyer might debit accounts payable by $200 and credit the relevant expense by $200. If the purchase was inventory or an asset, the offset may belong elsewhere. The buyer should use the supplier's credit-note reference to connect the adjustment.
If the invoice was already fully paid, the resulting value may be tracked as a receivable from the supplier or an account credit until settled. The precise posting depends on the system; avoid forcing an unpaid-invoice entry onto a paid-invoice refund.
Refund: record the bank movement separately
When you return money, reconcile the outgoing payment with the customer's credit. Processor fees may be retained, reversed, or charged separately according to your provider's terms. Do not hide them by changing the agreed credit amount without a valid basis.
Keep bookkeeping distinct from tax-return instructions. The IRS small-business tax guide addresses federal tax topics, but it is not a universal journal-entry manual for every business or entity type.
Tax and Legal Considerations: UK, EU, US, and Australia
Credit notes are widely used, but required fields, timing, and tax effects are not identical everywhere. The following is an orientation guide, not a substitute for advice on your transaction. Official sources were reviewed on 18 October 2026.
UK: a commercial credit is not automatically a VAT adjustment
HMRC's validity conditions include a genuine mistake, overcharge, or agreed reduction, and value being given to the customer. The guidance excludes credit notes issued for bad debts.
Be careful with the often-repeated “14 days” rule. HMRC's guidance on decreases in consideration ties the timing described there to the refund and says the credit note must be issued within 14 days of that refund. Do not turn that into a blanket deadline for every commercial correction.
Check when output VAT and the customer's input VAT should change. Merely generating a PDF does not establish that every condition for adjusting a VAT return has been met.
EU: identify the original invoice unambiguously
Article 219 of the EU VAT Directive treats an amending document as an invoice when it refers specifically and unambiguously to the initial invoice. This supports clear original-invoice references, not one universal credit-note template.
National requirements still matter. Consult the European Commission's invoicing overview and the relevant national authority for applicable fields and processes.
US: distinguish commercial records from tax treatment
“Credit memo” is common terminology. A documented adjustment can help align the customer's balance and your sales records, but there is no single credit-note instruction that settles every federal income-tax, state sales-tax, and entity-specific question.
Check the rules for the relevant state and transaction when sales tax was charged. Do not assume a bookkeeping credit automatically creates an identical tax deduction or permits a tax refund.
Australia: check adjustment-note requirements for GST
The ATO's adjustment-note guidance explains when a valid adjustment note is needed for decreasing GST adjustments, including exceptions such as GST adjustments of A$75 or less.
A general document headed “Credit Note” is not automatically a valid GST adjustment note. Check the required information, the adjustment event, and the applicable reporting treatment.
How to Handle Tax, Currency, and Multiple Credits
For a simple illustration only, suppose a taxable sale was $1,000 net plus $200 tax at a hypothetical 20% rate. Crediting $100 net at that same rate gives a $20 tax adjustment and a $120 total credit. The corrected gross charge would be $1,080 before considering payments.
That arithmetic is not a universal tax rule. Mixed rates, exempt supplies, tax-inclusive pricing, reverse charges, and rounding may require different handling. Show the affected lines and ask an adviser how to report the change.
Keep the credit in the original invoice currency. If a bank refund happens in another currency, document the exchange rate and any differences separately. Do not subtract a €200 credit directly from a $1,000 invoice as if the currencies were interchangeable.
For multiple credits, maintain a running total against the same invoice. Review earlier adjustments before approving another one. Credits allocated against the charge should not accidentally exceed that charge; separate any additional goodwill payment rather than disguising it as a correction to items never billed.
An Email to Send With a Credit Note
Subject: Credit note CN-0018 for invoice INV-0042
Hi [Name],
As agreed, we have issued credit note CN-0018 for $200 against invoice INV-0042 to remove the cancelled deliverable.
The original invoice was $1,000. With your $600 payment and this $200 credit applied, the remaining balance is $200. Please allocate the attached credit note against INV-0042 in your records.
[Confirm the applicable payment date, or state the refund amount and method if a refund is due.]
Please let us know if your statement shows a different balance so we can reconcile it together.
Thanks,
[Name]
For a fully paid invoice, replace the balance paragraph with the agreed refund or customer-credit arrangement. Avoid guaranteeing a refund arrival date unless your provider has confirmed it. Use our invoice email generator for subsequent payment follow-ups, not as a substitute for the credit-note document.
Common Credit Note Mistakes to Avoid
- Deleting the history: retain the original invoice and the correction so both sides can reconcile them.
- Confusing a credit with cash: check payments before promising a refund.
- Leaving the credit unallocated: an unapplied customer credit may not change the invoice your reminder system is chasing.
- Adjusting tax mechanically: follow applicable rules, not just the invoice's headline percentage.
- Crediting a bad debt as a billing error: inability to collect and a genuine price reduction are different events.
- Double-counting the adjustment: do not reduce the invoice manually and then apply the same credit again.
- Using a vague reference: identify the original invoice and affected items explicitly.
After posting a credit, check the customer statement and your accounts receivable aging report. A credit reduces the amount collectible; it does not mean your collections team received that amount in cash. Keep that distinction clear when reviewing DSO and collection performance.
Frequently Asked Questions About Credit Notes
Is a credit note the same as a credit memo?
The terms commonly describe the same kind of document: a reduction to a previously issued invoice. Credit memo is especially common in US accounting software. Check local requirements rather than relying on the name alone.
Is a credit note a refund?
No. A credit note documents a billing reduction. A refund returns money already collected. An unpaid invoice can be reduced without a refund, while a fully paid invoice may need both a credit note and a separate refund.
Who issues a credit note?
The seller normally issues the credit note to the customer for an agreed adjustment to the seller’s invoice. The customer records it against the corresponding purchase and payable, using the original invoice reference.
How do you calculate the balance after a credit note?
For an invoice with no payment reversals, subtract allocated payments and allocated credits from the original invoice total. A $1,000 invoice with $600 paid and a $200 allocated credit leaves $200 payable.
Can you issue a credit note for a partly paid invoice?
Yes. Check the corrected charge against payments already received. A credit may reduce the remaining balance or, if payments exceed the corrected charge, create excess payment that needs a refund or agreed customer-credit settlement.
What happens to a credit note on a paid invoice?
The reduction can create value owed back to the customer. Settle it through a refund or an appropriate agreed customer account credit. Record the cash movement separately and follow applicable customer and tax rules.
Does a credit note need the original invoice number?
Include a specific original-invoice reference so both businesses can trace the adjustment. EU VAT Article 219 addresses amending documents that refer specifically and unambiguously to the initial invoice. Additional local requirements may apply.
Does a credit note change VAT or sales tax?
It may require a tax adjustment, but generating the document alone does not establish the applicable tax treatment. Check the reason for the reduction, affected lines, local conditions, and reporting rules.
Should you issue a credit note for an overdue invoice?
Not merely because it is overdue. A genuine billing reduction and a bad debt are different events. If the full charge remains valid, use the appropriate collections or bad-debt process rather than recording a false price correction.
Can you use a credit note against a future invoice?
A customer credit may be held and allocated to a later invoice where appropriate and agreed. Document the arrangement and do not substitute future credit for a refund when applicable rules or the customer’s rights require money back.
Can an invoice generator create a compliant credit note?
Do not assume it can. Use a dedicated accounting-system credit-note function or a checked document workflow that meets applicable requirements. This guide does not claim Can You Pay That provides a dedicated credit-note or refund feature.
The Bottom Line
A credit note answers “what changed in the bill?” A refund answers “what money went back?” Keep those questions separate, reference the original invoice, and reconcile the resulting balance before sending another reminder.
Start with clear original invoices using our free invoice generator, then handle adjustments in your accounting system. A traceable correction protects the customer relationship without losing the transaction history.